The most common question we are asked about Singapore climate reporting is not what to disclose. It is when the obligation starts.
That is a reasonable question, because the answer depends on several variables at once -- whether the company is listed, whether it is an index constituent, its market capitalisation, and for non-listed companies its revenue and assets -- and because the timelines have been revised since they were first announced.
This article sets out how the phasing is structured. It is not a substitute for confirming your own position against current ACRA and SGX RegCo guidance, which is the first thing we do at the start of a reporting engagement.
The starting point: all listed companies report Scope 1 and 2
The baseline requirement is that SGX-listed companies report Scope 1 and Scope 2 greenhouse gas emissions from FY2025. This applies across listed issuers rather than only to the largest.
For many companies this is the first obligation that requires an actual measurement process rather than a narrative disclosure. It is worth being clear about what it demands: a defined organisational boundary, activity data for the reporting period, documented emission factors, and a figure that can be explained.
Further requirements are phased by index and size
Beyond the Scope 1 and 2 baseline, the remaining ISSB-based climate reporting requirements are introduced in stages.
Straits Times Index constituents are furthest ahead, with mandatory Scope 3 disclosure beginning in 2026. For other listed companies, Scope 3 initially remains voluntary, and the broader climate reporting requirements begin later -- from FY2028 for companies above a one billion dollar market capitalisation, and from FY2030 for those below it.
Large non-listed companies enter the regime later still. The threshold is defined by both revenue and assets, and Scope 1 and 2 reporting begins in 2030.
- STI constituents: Scope 3 disclosure mandatory from 2026
- Listed companies above S$1bn market capitalisation: remaining ISSB-based requirements from FY2028
- Listed companies below S$1bn market capitalisation: from FY2030
- Large non-listed companies meeting the revenue and asset thresholds: Scope 1 and 2 from 2030
Assurance follows reporting, on its own timetable
Reporting and assurance are phased separately. Limited assurance on Scope 1 and 2 data is being introduced after the reporting obligation itself, and the deadlines have been extended for some groups -- the STI constituent deadline moved from FY2027 to FY2029, and large non-listed companies are scheduled from 2032.
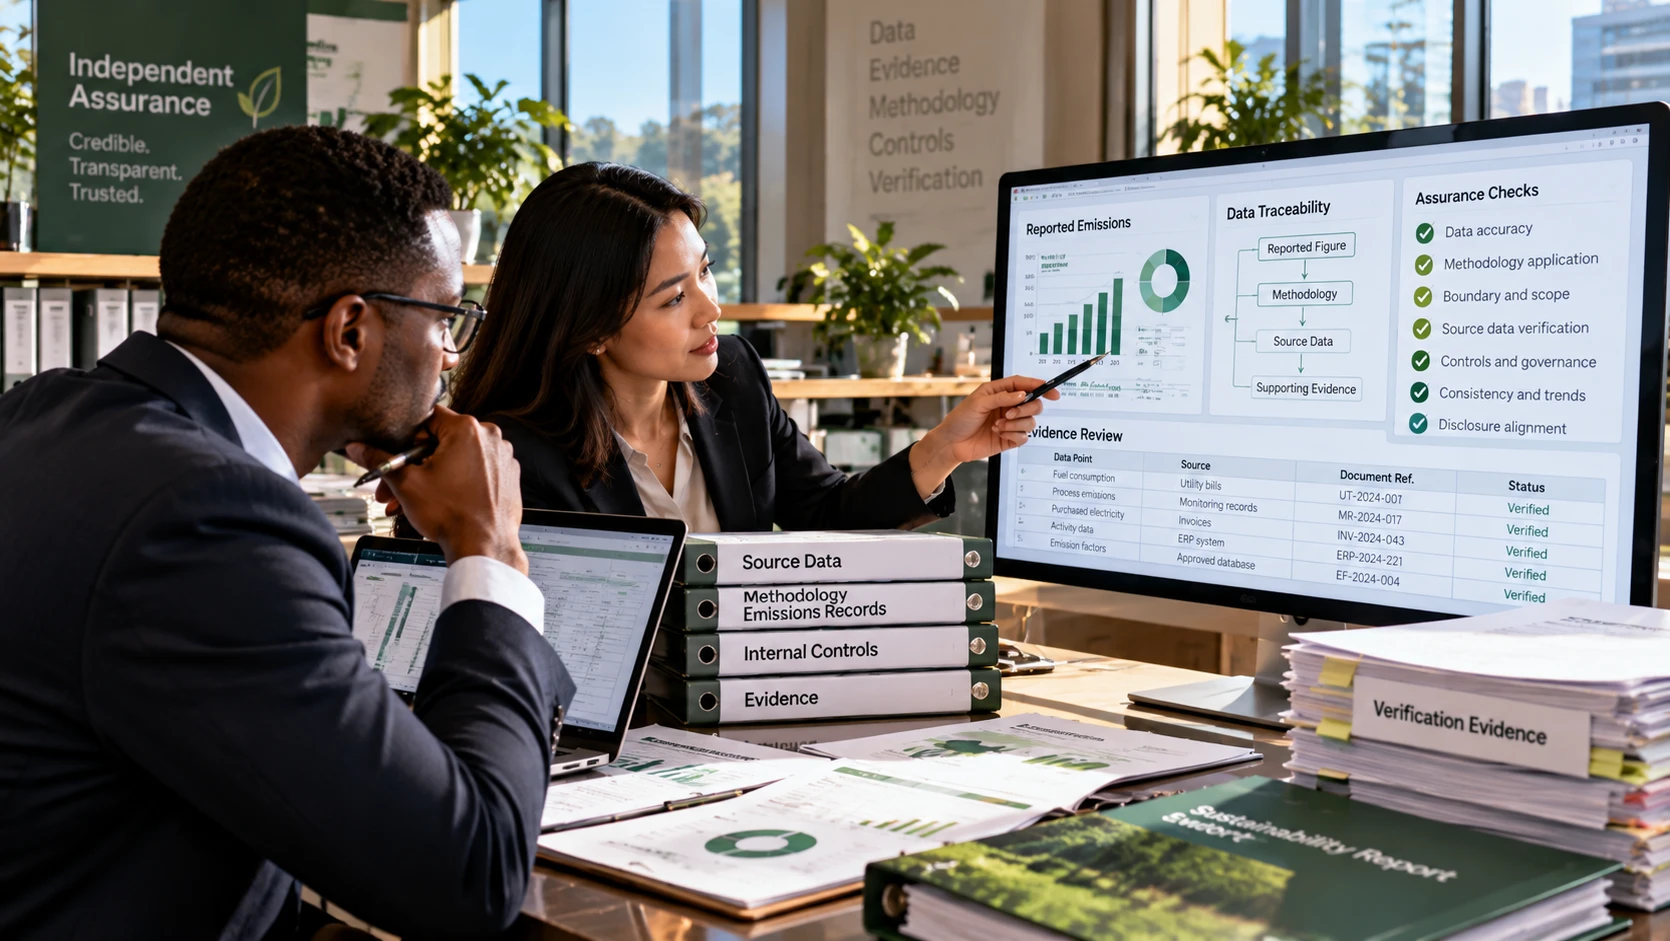
The extension is easily misread as time to defer preparation. In practice it is the opposite. Assurance tests evidence and process, and evidence cannot be created retrospectively. If source records for a reporting period were never retained, no amount of later effort reconstructs them.
The practical implication is that data reported now should be built to a standard that would survive assurance later, even where assurance is years away.
Why the timelines keep moving
ACRA and SGX RegCo have revised the implementation timelines, extending some deadlines by a significant margin, with the stated intention of giving smaller companies more time to prepare.
That is worth taking seriously as a planning assumption in both directions. Dates published in an article -- including this one -- can be superseded. Any organisation making resourcing decisions on the basis of a reporting date should verify it against current regulator guidance rather than a secondary summary.
What to do with this
Three practical steps follow from the structure above.
First, establish your own position precisely: listing status, index membership, market capitalisation, and for non-listed entities revenue and assets against the thresholds. This determines everything else.
Second, separate the reporting date from the preparation date. Organisations that begin building measurement capability in the year the obligation applies are generally too late, because the first reporting cycle exposes data gaps that take a cycle to close.
Third, build for assurance from the outset. The marginal cost of documenting methodology and retaining evidence while the work is being done is small. The cost of reconstructing it later is not.
Topics
- Singapore
- ISSB
- SGX
- ACRA
- Climate reporting