Raymond Cheung
Advisor & Lead Trainer
Over twenty years in actuarial science and risk management, working across ESG, sustainability and ESG investment.
Actuarial science · Risk management · ESG and sustainability
View Raymond Cheung’s profile// Carbon & Climate
Establish which emissions you are accountable for, and measure the ones that matter.
Complete Scope 1 and 2 measurement, and a Scope 3 programme that starts with screening and prioritisation rather than attempting fifteen categories at once.
// Context
Scope 1 and Scope 2 cover emissions an organisation controls directly or through its purchased energy. They are bounded, and for most organisations they are the smaller number.
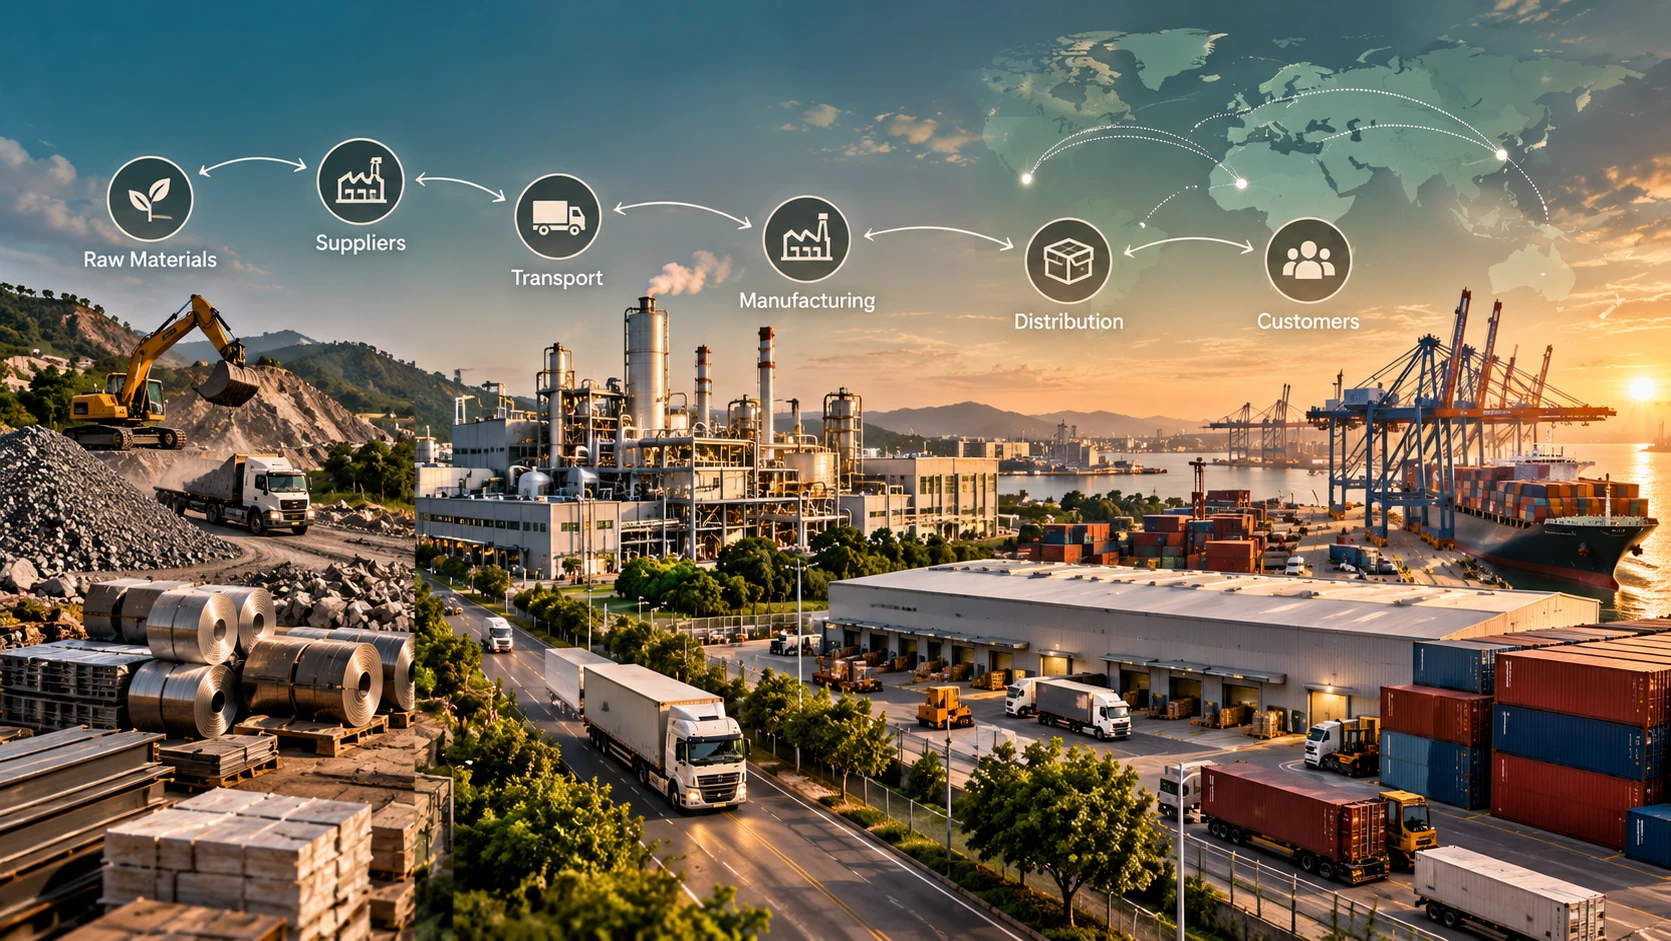
Scope 3 covers the value chain -- purchased goods and services, transport, use of sold products, and eleven further categories. For many businesses it accounts for the large majority of total emissions, and it is the part that customers and investors increasingly ask about.
Attempting all fifteen Scope 3 categories in a first year is a common and expensive mistake. Screening first establishes which categories are material to this business, which are measurable with the data available, and which can wait.
// The engagement
// Deliverables
// Fit
// Why CER
CER works from Singapore with organisations across Asia, which matters for this service because requirements arriving from European regulators, regional supervisors and local listing rules do not align neatly.
Engagements run through to implementation: the data collection process, the documentation, the controls and the internal handover, so that the second cycle is cheaper than the first and can be run without us.
Where an organisation would be better served by building the capability internally, CER Academy delivers the same technical material as training.
Meet the people behind the work// Our people
Advisor & Lead Trainer
Over twenty years in actuarial science and risk management, working across ESG, sustainability and ESG investment.
Actuarial science · Risk management · ESG and sustainability
View Raymond Cheung’s profile// Questions
Location-based uses the average emissions intensity of the grid you draw from. Market-based reflects the electricity you have contractually procured, including renewable energy instruments. The GHG Protocol requires both to be reported where a market-based figure is claimed.
No. The Scope 3 Standard requires you to screen all fifteen and report those that are material, disclosing and justifying any exclusions. Screening is what makes that judgement defensible.
Under the phased SGX approach, mandatory Scope 3 reporting begins with STI constituents. For other listed companies Scope 3 initially remains voluntary. Because these timelines have been revised, we confirm the current position against ACRA and SGX RegCo guidance at the point of engagement.
Most organisations start with spend-based or average-data methods, which are accepted under the standard, then move priority suppliers onto primary data over time. The route from one to the other should be planned rather than left open.
Emissions do appear in more than one organisation's Scope 3 inventory, and that is by design. Scope 3 measures value-chain influence, not exclusive ownership of a tonne. It is not added to national inventories.
// Related
A defensible greenhouse gas number, built on a documented boundary, traceable data and a methodology that stays consistent between reporting years.
Carbon Accounting: Explore this serviceA complete organisational inventory with defined boundaries, documented sources, quality controls and a base year you can report against consistently.
GHG Inventory Development: Explore this serviceSupplier requirements, assessment criteria and contract terms that make sustainability part of procurement decisions and give you the supply-chain data you are being asked for.
Sustainable Procurement: Explore this serviceProduct-level assessment following ISO 14040 and ISO 14044, from goal and scope definition through inventory analysis, impact assessment and interpretation.
Life Cycle Assessment: Explore this service// Sectors
Carbon measurement, Scope 3, supply-chain requirements and sustainable procurement.
Manufacturing & Supply Chain: View sector expertiseData centre and cloud emissions, purchased energy, supply-chain hardware and customer ESG requirements.
Technology: View sector expertise// Insights
Most organisations approach Scope 3 by trying to measure everything. Screening first is faster, cheaper and produces a more defensible result.
3 min read
Scope 3: where to start when fifteen categories is not a plan: Read articleTell us where you are now and what you are being asked for. We will tell you what closing that gap actually involves.
Building this capability internally instead? CER Academy delivers the same technical material as training.
We use necessary cookies to make this site work. We would also like to set analytics cookies to understand how the site is used. Nothing beyond the necessary cookies is set without your agreement. Read the cookie policy.